Visual Intelligence · Global Economy Maps
Global Logistics Corridors 2026
Analyze 2026 global logistics corridors, trade route shifts, infrastructure investments, and geopolitical supply chain risks for institutional portfolios.
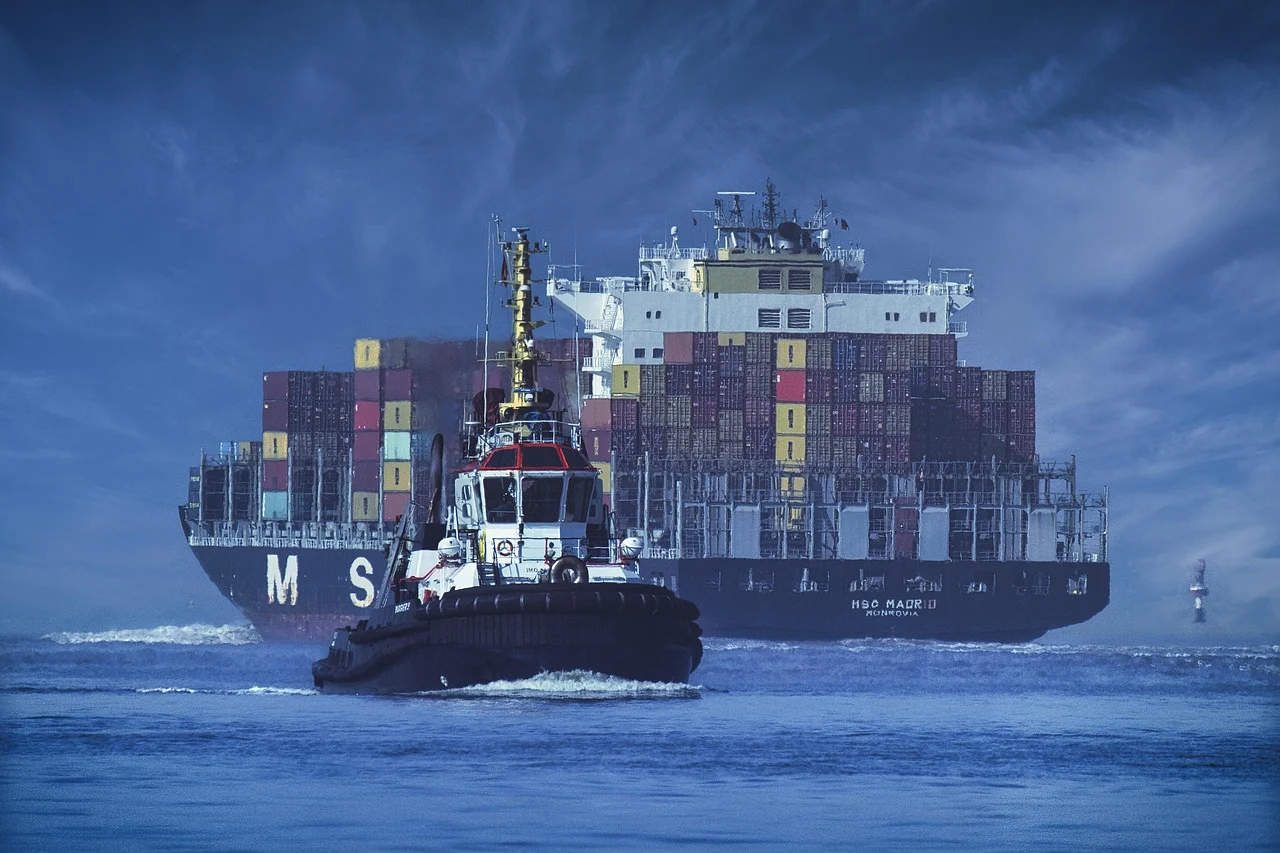
Table of Contents
- Strategic Realities of Transcontinental Trade
- The Evolution of Maritime Trade Routes
- Choke Point Vulnerabilities and Capital Exposure
- Navigational Shifts and Polar Alternates
- Economic Drivers of Supply Chain Fragmentation
- The Economics of Redundancy and Buffer Stock
- Sovereign Industrial Policies and Tariff Architecture
- Capital Deployment in Nearshoring Infrastructure
- Industrial Real Estate and Logistics Hubs
- Energy and Power Grid Modernization
- Integration of Transcontinental Freight Networks
- Rail Freight Economics and Continental Connectivity
- Digital Customs and Border Friction Reduction
- Comparative Analysis of Major Global Logistics Corridors
- Frequently Asked Questions
- How do disruptions in primary maritime choke points impact institutional equity valuations?
- What role do sovereign industrial policies play in restructuring transcontinental freight?
- Why are institutional investors heavily allocating capital toward industrial real estate nearshoring hubs?
- How does digital customs modernization reduce systemic friction in transcontinental trade?
- Conclusion and Future Outlook
9 min read
Strategic Realities of Transcontinental Trade
Capital allocation strategies for multinational corporations and institutional investors are increasingly dictated by the physical infrastructure, sovereign risk profiles, and operational throughput of Global Logistics Corridors. As globalization undergoes a structural metamorphosis, the classical paradigm of frictionless, just-in-time international commerce has yielded to an era characterized by resilience, redundancy, and risk-weighted routing. International investors and treasury professionals can no longer view physical distribution networks as static operational variables; instead, these arteries of international exchange represent fundamental determinants of enterprise valuation, sovereign credit risk, and asset-backed capital expenditure efficiency. The confluence of geopolitical friction, extreme weather events driven by climate shifts, and the weaponization of economic dependencies has elevated supply chain architecture to the boardroom level, demanding sophisticated quantitative evaluation and proactive asset deployment.
The Evolution of Maritime Trade Routes
Historically, the architecture of international commerce relied upon predictable oceanic thoroughfares governed by bilateral trade pacts and stable geopolitical norms. Today, the foundational economics of maritime trade routes are experiencing radical compression and volatility. Maritime transit accounts for approximately eighty percent of global trade volume by weight, concentrating systemic risk within critical oceanic bottlenecks such as the Strait of Malacca, the Bab el-Mandeb, the Suez Canal, and the Panama Canal. When these choke points experience disruption—whether through regional military conflict, drought-induced capacity constraints, or labor disputes—the ripple effects destabilize global manufacturing inputs, inflate working capital requirements, and trigger inflationary impulses across sovereign economies.
Choke Point Vulnerabilities and Capital Exposure
The strategic vulnerability of primary maritime arteries forces institutional capital to re-evaluate the risk premiums associated with ocean freight. For instance, disruptions in the Red Sea corridor compel mega-containership operators to bypass the Suez Canal entirely, diverting vessels around the Cape of Good Hope. This diversion adds approximately 3,500 to 4,500 nautical miles per voyage, extending transit times by ten to fourteen days and exponentially increasing bunker fuel expenditures. Treasury departments must maintain significantly larger liquidity buffers to absorb extended cash conversion cycles, while corporate risk managers contend with heightened cargo insurance premiums and vessel charter rates. The financial exposure inherent in these operational contingencies underscores the necessity of multi-modal asset allocation strategies.
Navigational Shifts and Polar Alternates
As traditional shipping lanes face structural headwinds, exploratory capital is flowing toward alternative high-latitude routes, most notably the Northern Sea Route across the Russian Arctic. While melting sea ice theoretically reduces transit distances between East Asian ports and Northern European hubs by up to forty percent compared to southern routes via the Suez Canal, the capital expenditure required to establish dependable deep-water port facilities, icebreaker escorts, and search-and-rescue infrastructure remains cost-prohibitive for private consortia without substantial sovereign backing. Furthermore, the regulatory, environmental, and geopolitical complexities of operating within Arctic waters introduce risk profiles that many institutional asset managers deem misaligned with fiduciary mandates.
Economic Drivers of Supply Chain Fragmentation
The unbundling of hyper-optimized supply chains represents a profound structural shift away from single-source manufacturing paradigms. Driven by escalating labor costs in traditional manufacturing centers, punitive tariff regimes, and the systemic vulnerabilities exposed during global health crises, enterprises are actively pursuing multi-nodal sourcing frameworks. This ongoing supply chain fragmentation introduces structural inefficiencies that permanently alter enterprise gross margins. Rather than minimizing cost-of-goods-sold through hyper-concentration in low-wage jurisdictions, modern corporate strategy prioritizes optionality, redundancy, and regional autonomy.
The Economics of Redundancy and Buffer Stock
Transitioning from lean, just-in-time inventory models to resilient, just-in-case architectures requires a fundamental re-engineering of corporate balance sheets. Holding higher levels of raw material buffer stock and finished goods inventory ties up substantial working capital, reducing return on capital employed for manufacturing and retail entities. However, institutional analysts evaluate this trade-off favorably when weighed against the catastrophic revenue losses associated with complete component stockouts. Consequently, private equity sponsors and corporate treasurers are actively investing in intelligent inventory management systems, predictive analytics, and automated warehousing to offset the carrying costs of decentralized inventory networks.
Sovereign Industrial Policies and Tariff Architecture
Governments worldwide are deploying aggressive industrial policies, direct subsidies, and protective tariffs to reshore or friendshore strategic manufacturing sectors, particularly semiconductors, green energy technology, and pharmaceuticals. Legislative frameworks such as the United States Creating Helpful Incentives to Produce Semiconductors Act and the European Union’s Net-Zero Industry Act inject hundreds of billions of dollars into domestic production ecosystems. For institutional investors, these capital deployment initiatives create bifurcated market conditions. Enterprises aligned with sovereign industrial priorities benefit from non-dilutive grant funding and tax credits, while companies reliant on legacy cross-border manufacturing must absorb rising compliance and tariff costs.
Capital Deployment in Nearshoring Infrastructure
The tactical redirection of manufacturing and assembly operations closer to final consumer markets has transformed regional real estate, transportation, and energy sectors. This structural pivot requires massive capital investments in nearshoring infrastructure, altering the economic landscape of recipient nations. Countries possessing strategic geographical proximity to major consumer markets, coupled with stable legal frameworks and robust labor pools, are experiencing historic influxes of foreign direct investment. This trend is prominently observable across North America, Central and Eastern Europe, and Southeast Asia.
Industrial Real Estate and Logistics Hubs
The surge in regional manufacturing has triggered unprecedented demand for modern industrial real estate, distribution centers, and multimodal freight terminals. Institutional real estate investment trusts and private wealth funds are aggressively acquiring land banks and developing Grade-A warehouse facilities equipped with advanced robotics, automated sorting systems, and sustainable energy features. These investments are increasingly concentrated in regions characterized by favorable supply chain finance dynamics that support agile manufacturing ecosystems. Markets near major consumption centers command premium valuations, reflecting their critical role in reducing last-mile delivery times and mitigating long-haul transport risks.
Energy and Power Grid Modernization
Industrial relocation and factory automation require reliable, high-capacity electrical grids capable of supporting heavy manufacturing, data centers, and electrified transport fleets. Nearshoring destinations often face immediate infrastructure bottlenecks, necessitating substantial capital outlays for power generation, transmission line upgrades, and smart grid deployment. Institutional investors specializing in infrastructure asset classes are finding lucrative opportunities in public-private partnerships designed to finance, construct, and operate the power and utility assets underpinning modern industrial parks. Without concurrent investments in power infrastructure, regional manufacturing expansion stalls, capping the long-term appreciation potential of industrial real estate assets.
Integration of Transcontinental Freight Networks
Bridging fragmented regional production hubs requires the seamless integration of transcontinental freight networks that combine rail, road, maritime, and air transport into unified corridors. These comprehensive networks are designed to optimize speed, cost, and carbon efficiency across massive geographic expanses. Mega-projects such as the Trans-European Transport Network and various continental trade corridors aim to harmonize gauge standards, digital customs procedures, and intermodal transfer points, significantly reducing transit friction.
Rail Freight Economics and Continental Connectivity
Rail transport serves as the backbone of transcontinental freight networks, offering a cost-effective and environmentally efficient alternative to long-haul trucking and air freight. High-capacity container trains capable of traversing continents provide predictable transit schedules that insulate shippers from maritime port congestion and oceanic weather volatility. Financial institutions and sovereign wealth funds are partnering to finance electrification projects, double-tracking initiatives, and digital signaling systems across critical rail corridors to maximize freight throughput and asset utilization.
Digital Customs and Border Friction Reduction
Physical infrastructure alone cannot guarantee efficient logistics performance without complementary regulatory harmonization and digital modernization. Customs clearance bottlenecks frequently introduce multi-day delays at international borders, neutralizing the time-savings achieved by high-speed rail or advanced maritime shipping. The implementation of blockchain-enabled documentation, single-window customs portals, and automated clearance protocols significantly accelerates border processing times. For a comprehensive overview of how digital transformation intersects with capital flows, institutional investors frequently examine macroeconomic trade intelligence reports that evaluate sovereign modernization efforts and technological adoption rates.
Comparative Analysis of Major Global Logistics Corridors
To evaluate the risk-adjusted returns and operational resilience of international trade networks, institutional analysts must compare the primary corridors governing world commerce. The following matrix outlines key economic and operational metrics across four critical transit pathways.
| Corridor Name | Primary Transport Modes | Principal Risk Factors | Capital Intensity | Relative Throughput Speed |
|---|---|---|---|---|
| Trans-Pacific Maritime Route | Container Shipping, Air Freight | Port Congestion, Geopolitical Tension, Weather | High (Vessels, Port Terminals) | Moderate to Slow |
| Asia-Europe Maritime Corridor | Mega-Container Ships, Rail Feeder | Choke Point Disruption (Suez, Bab el-Mandeb) | Very High (Fleet Scale, Infrastructure) | Slow |
| Trans-Eurasian Rail Landbridge | Container Rail, Intermodal Trucking | Sanctions, Geopolitical Borders, Gauge Changes | Moderate (Track Upgrades, Terminals) | Fast |
| North American Continental Corridor | Class I Rail, Interstate Trucking, Air | Labor Strikes, Border Inspection Delays | High (Highway, Rail Network Maintenance) | Fast |
Analyzing these parameters enables capital allocators to construct resilient portfolios that balance high-speed, higher-cost transport options with high-capacity, lower-cost alternatives, ensuring portfolio resilience against localized disruptions.
Frequently Asked Questions
How do disruptions in primary maritime choke points impact institutional equity valuations?
Disruptions in critical maritime corridors increase shipping costs, extend transit times, and cause inventory shortages for multinational corporations. These operational frictions compress gross margins, elevate working capital requirements, and force downward revisions in corporate earnings forecasts, directly depressing enterprise equity valuations.
What role do sovereign industrial policies play in restructuring transcontinental freight?
Sovereign industrial policies introduce targeted subsidies, tariffs, and regulatory mandates that incentivize corporations to relocate manufacturing operations closer to home markets. This shift reduces reliance on distant offshore suppliers, transforming transcontinental freight routes into more regionalized, multi-nodal distribution networks.
Why are institutional investors heavily allocating capital toward industrial real estate nearshoring hubs?
Investors target nearshoring logistics real estate to capture rental yield premiums driven by intense corporate demand for secure, proximate warehousing space. Holding inventory closer to final consumer markets mitigates long-haul transport risks and aligns with modern just-in-case supply chain strategies.
How does digital customs modernization reduce systemic friction in transcontinental trade?
Digital customs platforms utilize automated documentation, electronic data interchange, and blockchain verification to eliminate physical paperwork and manual inspections at borders. This modernization drastically shortens dwell times, reduces administrative overhead, and enhances predictability across international freight networks.
Conclusion and Future Outlook
The ongoing structural evolution of international commerce confirms that physical distribution networks are core determinants of economic resilience and corporate profitability. As geopolitical tensions, climate vulnerabilities, and industrial policy shifts continue to reshape global trade, the reliance on hyper-optimized, single-source logistics models has been permanently replaced by resilient, diversified architectures. Institutional investors, corporate executives, and financial analysts must embed these operational and sovereign risk variables directly into their capital allocation frameworks and valuation models. Ultimately, entities that successfully anticipate infrastructure bottlenecks, embrace multimodal transport optionality, and invest in digital logistics integration will capture superior risk-adjusted returns in the modern global economy.
Related: Middle East Sovereign Wealth Funds 2026
About the Author: Iqbal Hossain
Iqbal is the Founder and Lead Strategist of Global Investment Reviews. As a Financial Analyst and Geopolitical Strategist with over 7 years of experience, he specializes in connecting global events with market trends to help investors make informed, long-term decisions.
Related Analysis
Global Economy Maps
Geoeconomic Fragmentation Risks
Analyze the financial impact of geoeconomic fragmentation, supply chain decoupling, and multipolar currency systems on global investment portfolios.
Global Economy Maps
Global Trade Corridor Mapping
Explore how trade corridors connect ports, logistics hubs and infrastructure, and how geopolitical and supply-chain risks affect cross-border investment.
Global Economy Maps
Global Supply Chain Corridor 2026
Analyze shifting trade routes, nearshoring investments, and logistics infrastructure financing across key global economic corridors for 2026. Supply Chain Corri
The information provided is for educational and informational purposes only and does not constitute financial, investment, tax, or legal advice.