Calculate your future wealth with GIR Finance's SIP Calculator. Estimate returns on your monthly investments and plan your financial freedom easily.
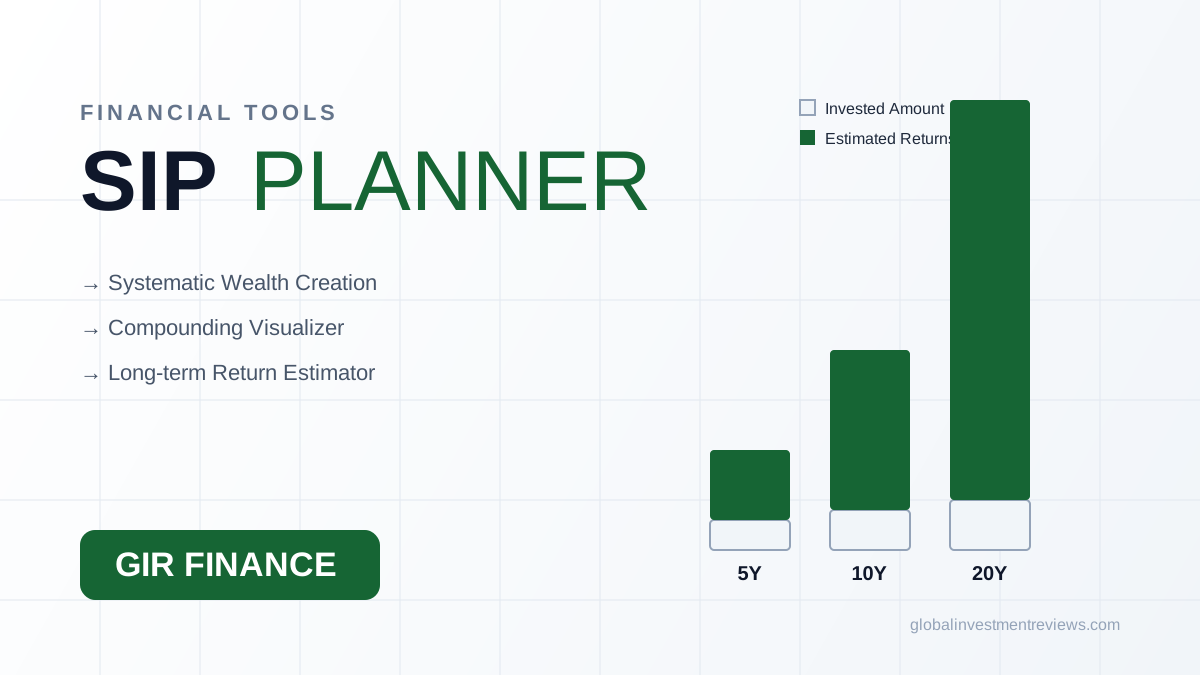
SIP Wealth Calculator
Plan Your Financial Future with Precision
Achieving long-term wealth starts with a smart strategy. Whether you are planning for retirement, building a college fund, or setting personal goals, our Online SIP Return Calculator provides the clarity you need. Beyond a standard Mutual Fund Systematic Investment Plan (SIP) Calculator, our advanced Step-up SIP calculator allows you to factor in annual income growth, ensuring your Wealth creation keeps pace with your lifestyle. Use our inflation-adjusted SIP calculator and goal-based investment calculator to visualize your financial trajectory with institutional-grade accuracy. Start your journey with GIR Finance today—calculate your potential SIP maturity value and take control of your financial freedom.
SIP in Action: Real-Life Wealth Building Scenarios
Understanding the mathematical potential of a Systematic Investment Plan is easier with practical examples. Here are three distinct scenarios based on different investor profiles.
1. The Power of Starting Early
Alex (Age 25) starts a monthly SIP of $100 for 30 years.
• Total Invested: $36,000
• Est. Return (12%): ~$350,000
By starting early, Alex allows compounding to work for three decades, turning a small habit into a massive retirement fund.
2. High-Value Short Horizon
Sarah (Age 40) wants to build a college fund. She invests $1,000 monthly for 10 years.
• Total Invested: $120,000
• Est. Return (12%): ~$230,000
Even with a shorter time frame, a larger contribution combined with market returns nearly doubles her money.
3. The Step-Up Strategy
David starts with $200 but increases his SIP by 10% every year as his salary grows.
David will accumulate nearly 60% more wealth compared to a fixed SIP over 15 years, effectively beating inflation and accelerating his financial freedom.
Expert FAQ: Strategic SIP Planning
1. What is the fundamental advantage of a SIP? ↓
2. How does the GIR Finance calculator determine future value? ↓
3. Why is compounding often called the "Eighth Wonder"? ↓
4. Can a SIP help me achieve specific life goals? ↓
5. What is a "Step-up SIP" and why should I use it? ↓
6. Is it possible to lose money in a SIP? ↓
7. How are long-term SIP returns taxed? ↓
8. When is the best time to stop a SIP? ↓
9. Can I pause my SIP contributions? ↓
10. What makes the GIR Finance SIP Calculator unique? ↓
A practical note on SIP Calculator
The question worth answering: This page is most useful when you focus on modelling regular investing without assuming a smooth market. Estimating the future value of periodic contributions under a chosen return assumption. Start by recording the input source, the date or period covered, and any assumption you had to supply yourself. That makes the result easier to reproduce and helps another person understand what the output actually says.
How to use the result responsibly
Read the output alongside the inputs rather than as a stand-alone verdict. Change one assumption at a time and observe whether the conclusion changes materially. If the tool accepts a range, test more than one plausible case; if it accepts a file or pasted data, preserve an untouched copy of the original. Where the result will support a published claim or an important decision, keep a brief record of the method and source date.
A mistake specific to this kind of task
A constant monthly return does not resemble actual market paths, and the final value can differ substantially when returns arrive in a different order. This is why the output should be described as an estimate, diagnostic or comparison where appropriate—not as a guarantee. Avoid mixing currencies, periods, definitions or data sources merely because their labels look similar.
Independent check before acting
Compare conservative and optimistic scenarios, confirm contribution timing and distinguish a mathematical projection from a promised outcome. If the result conflicts with a statement, official record, provider terms or the original dataset, investigate the difference before relying on it. The tool is intended to make a task clearer, not to replace the source system or professional advice when the consequences are material.
Reader takeaway: Keep the assumptions visible, verify the underlying evidence and use this result as one part of a reasoned decision.
Related Resources
SIP Top-up Calculator
Model how increasing your systematic investment plan (SIP) contribution over time may affect total contributions and projected investment value with GIR’s SIP Top-up Calculator.
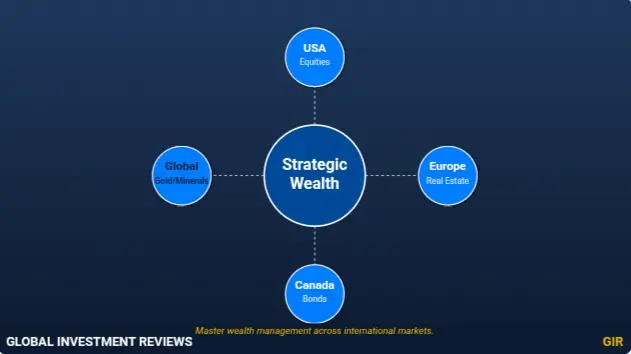
Wealth Management
Strategic Wealth Management for Global Investors: The Definitive Guide to Long-Term Prosperity
Master strategic wealth management for global investors with 20+ years of insights. Build a resilient portfolio and secure long-term financial growth with GIR.
Wealth Management
Cross-Border Wealth Structuring
Master cross-border wealth structuring for international assets. Explore jurisdiction selection, multi-jurisdictional estate planning, and tax efficiency.