

Digital Transformation and Fintech Expansion Across the South Pacific Markets
Table of Contents
- Macroeconomic Drivers of Contemporary Liquidity Dynamics
- Corporate Treasury Perspectives: Optimizing Working Capital and Cash Equivalents
- Institutional Portfolio Management and Asset Allocation Implications
- Comparative Analysis of Liquidity Management Instruments
- Risk Factors and Counterparty Vulnerabilities
- Frequently Asked Questions
- Question: How do central bank quantitative tightening programs impact corporate treasury liquidity management?
- Question: What constitutes an effective liquidity buffer for an institutional asset owner?
- Question: How should treasurers mitigate counterparty risk in short-term cash investments?
- Question: What is the primary risk of relying on money market funds for operational cash?
- Conclusion and Future Outlook
Digital Transformation and Fintech Expansion Across the South Pacific Markets is an important topic covered by Global Investment Reviews.
Navigating modern macroeconomic volatility requires institutional asset allocators and corporate treasurers to develop a sophisticated understanding of liquidity management in global financial markets. As central banks across developed economies balance persistent structural inflation with the fragilities of over-leveraged sovereign and corporate balance sheets, traditional cash-equivalents face unprecedented stress. Global liquidity is no longer a static balance sheet cushion; it functions as a dynamic, highly sensitive variable directly impacted by quantitative tightening, regulatory capital mandates, and shifting cross-border capital flows. For institutional portfolios and corporate treasuries, the ability to maintain robust liquidity buffers while optimizing yield has transformed from a routine administrative function into a critical driver of enterprise survival and strategic optionality.
Macroeconomic Drivers of Contemporary Liquidity Dynamics
The architecture of global liquidity has fundamentally shifted since the post-financial crisis era of quantitative easing. Central bank balance sheet normalization—commonly referred to as quantitative tightening—has systematically drained excess reserves from the global banking system. This withdrawal of central bank liquidity interacts directly with commercial bank lending constraints enforced by Basel III regulatory frameworks, including the Net Stable Funding Ratio and the Liquidity Coverage Ratio.
Consequently, wholesale funding markets exhibit heightened sensitivity to episodic stress. When primary dealers face balance sheet capacity constraints, the transmission mechanism of monetary policy can experience sudden friction. This manifests as widening bid-ask spreads in sovereign debt markets, periodic spikes in overnight repo rates, and compressed depth in secondary corporate bond markets. Institutional investors must recognize that nominal liquidity—the presence of a quoted market price—often diverges significantly from effective execution liquidity during periods of market distress.
Structural shifts in international trade settlement and geopolitical fragmentation have also altered the geography of capital. Fragmentation risks driving a balkanization of liquidity pools, forcing multinational corporations to manage localized currency squeezes rather than relying on centralized global treasury pooling. Understanding these macroeconomic vectors is essential for anticipating liquidity shocks before they compromise portfolio asset allocation or corporate operational continuity.
Corporate Treasury Perspectives: Optimizing Working Capital and Cash Equivalents
For corporate executives and treasury professionals, managing enterprise liquidity requires balancing three competing mandates: safety, liquidity, and yield. In an environment characterized by elevated interest rates, the opportunity cost of holding idle cash is substantial, yet the systemic risks associated with counterparty credit exposure and duration mismatch preclude aggressive risk-taking in short-term portfolios.
Effective corporate liquidity architecture begins with granular cash-flow forecasting paired with dynamic stress-testing. Rather than relying on static historical cash buffers, sophisticated treasurers employ scenario-based modeling to evaluate liquidity resilience under severe operational disruptions, supply chain shocks, or sudden credit rating downgrades. This approach dictates the optimal tiering of cash assets across distinct functional buckets:
- Tier 1 Operational Cash: Immediate transaction balances held in central bank-backed deposit accounts or immediate-access money market funds designed for daily settlement and payroll obligations.
- Tier 2 Reserve Liquidity: Short-duration instruments, including treasury bills, prime commercial paper, and high-grade negotiable certificates of deposit, structured to match anticipated quarterly outflows.
- Tier 3 Strategic Reserves: Flexible capital allocations positioned in ultra-short bond funds or managed separately managed accounts designed to capture yield premiums without compromising secondary market marketability.
By enforcing strict counterparty diversification limits and utilizing tri-party repo arrangements backed by pristine sovereign collateral, treasurers mitigate systemic financial contagion risks while maintaining operational agility.
Institutional Portfolio Management and Asset Allocation Implications
For institutional investors, portfolio liquidity dictates the boundaries of active risk-taking and asset liability management. Pension funds, sovereign wealth funds, and endowment managers operate under strict liquidity constraints dictated by ongoing liability payouts, capital calls from private market commitments, and potential margin calls on derivative overlays.
The rapid growth of private markets—including private equity, private credit, and infrastructure debt—has introduced structural illiquidity into portfolios historically dominated by liquid public equities and fixed income. While these illiquid asset classes offer attractive long-term risk-adjusted return premiums, they create significant cash-flow matching challenges during market downturns when public market valuations decline and distribution flows from private funds dry up.
Institutional allocators must maintain a robust liquidity denominator framework. This involves calculating the true cash realization timeline of portfolio holdings under distressed liquidation scenarios. It also requires establishing explicit liquidity budgets that restrict commitments to illiquid strategies based on projected secondary market liquidity of remaining public assets. Failing to account for second-order liquidity drains often forces asset owners to become forced sellers of high-quality liquid assets at distressed valuations during market dislocations.
Comparative Analysis of Liquidity Management Instruments
Selecting appropriate liquidity instruments demands a rigorous evaluation of yield, credit risk, duration risk, and institutional marketability. The following structured comparison details the primary instruments utilized by sophisticated market participants for managing short-term capital.
| Instrument Category | Primary Credit Risk | Average Duration / Maturity | Secondary Market Liquidity | Typical Yield Profile |
|---|---|---|---|---|
| Sovereign Treasury Bills | Sovereign Risk (Minimal for G7) | 1 to 12 Months | Deep and Continuous | Risk-Free Benchmark Rate |
| Prime Commercial Paper | Corporate / Financial Issuer Risk | Overnight to 270 Days | Moderate (Active Dealer Market) | Sovereign Rate + Credit Spread |
| Money Market Mutual Funds | Diversified Short-Term Portfolio | Weighted Average Maturity < 60 Days | Daily Redemption (T+0 / T+1) | Competitive Short-Term Rate |
| Tri-Party Repurchase Agreements | Collateral / Counterparty Risk | Overnight to Term (1–90 Days) | High (Collateral Backed) | Secured Financing Rate (SOFR-based) |
| Negotiable Certificates of Deposit | Banking Sector Credit Risk | 30 Days to 5 Years | Variable (Dealer Dependent) | Interbank Rate + Premium |
Risk Factors and Counterparty Vulnerabilities
Liquidity management is inextricably linked to risk management, specifically concerning counterparty exposure and settlement friction. During episodes of acute market stress, correlations across asset classes converge toward one, and traditional liquidity providers often pull back from market-making activities. This withdrawal exacerbates price volatility and creates severe execution penalties for large institutional block trades.
Counterparty risk requires rigorous continuous monitoring, particularly in over-the-counter derivatives and secured lending markets. Reliance on single-dealer financing lines exposes corporations and investment funds to sudden margin calls or credit facility contractions. Diversifying banking relationships, utilizing central clearinghouses where feasible, and maintaining excess unencumbered collateral buffers are critical operational defenses against unexpected counterparty failures.
Regulatory developments surrounding non-bank financial intermediaries—such as open-ended mutual funds, hedge funds, and pension funds utilizing leveraged strategies—remain a focal point for global financial stability monitors. A forced asset fire sale within one segment of the non-bank financial ecosystem can rapidly cascade across global funding markets, impairing asset values and restricting credit availability for the broader corporate sector.
Frequently Asked Questions
Question: How do central bank quantitative tightening programs impact corporate treasury liquidity management?
Answer: Quantitative tightening reduces aggregate bank reserves and wholesale liquidity within the financial system. For corporate treasurers, this typically manifests as higher borrowing costs in short-term debt markets, tighter commercial paper capacity, and increased volatility in overnight funding rates, requiring more conservative cash-buffer sizing and tighter counterparty monitoring.
Question: What constitutes an effective liquidity buffer for an institutional asset owner?
Answer: An effective institutional liquidity buffer comprises unencumbered, high-quality liquid assets capable of immediate monetization without significant price concessions. It must be calibrated using dynamic cash-flow stress testing that accounts for private market capital call pacing, derivative margin requirements, and liability payout obligations under distressed market scenarios.
Question: How should treasurers mitigate counterparty risk in short-term cash investments?
Answer: Treasurers mitigate counterparty risk by enforcing strict issuer diversification, favoring collateralized structures such as tri-party repurchase agreements backed by sovereign debt, maintaining ongoing credit surveillance of banking partners, and adhering to maximum exposure limits based on external credit ratings and internal risk models.
Question: What is the primary risk of relying on money market funds for operational cash?
Answer: While institutional money market funds offer high liquidity and diversification, primary risks include potential exposure to financial sector credit stress, regulatory redemption gates or liquidity fees during severe market dislocations, and the risk of breaking the buck in prime funds during extreme credit crises.
Conclusion and Future Outlook
The structural transformation of global monetary policy and banking regulation dictates that liquidity management can no longer be treated as a passive, administrative back-office function. For international investors, corporate executives, and institutional market participants, maintaining financial resilience demands continuous strategic oversight, rigorous scenario modeling, and dynamic asset-liability alignment. As structural inflation pressures, geopolitical fragmentation, and central bank balance sheet adjustments continue to reshape the global financial architecture, organizations that proactively fortify their liquidity frameworks will preserve operational flexibility, protect capital value, and position themselves to capitalize on episodic market dislocations.
Iqbal Hossain
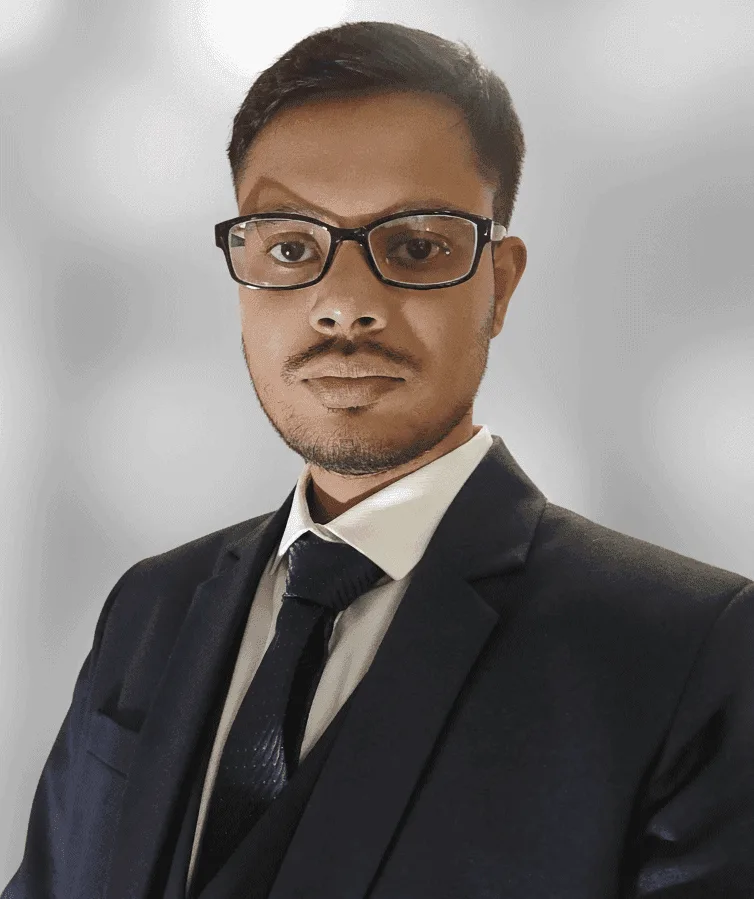
About the Author: Iqbal Hossain
Iqbal is the Founder and Lead Strategist of Global Investment Reviews. As a Financial Analyst and Geopolitical Strategist with over 7 years of experience, he specializes in connecting global events with market trends to help investors make informed, long-term decisions.


